
Private 5G Is a Building-Block Play Now
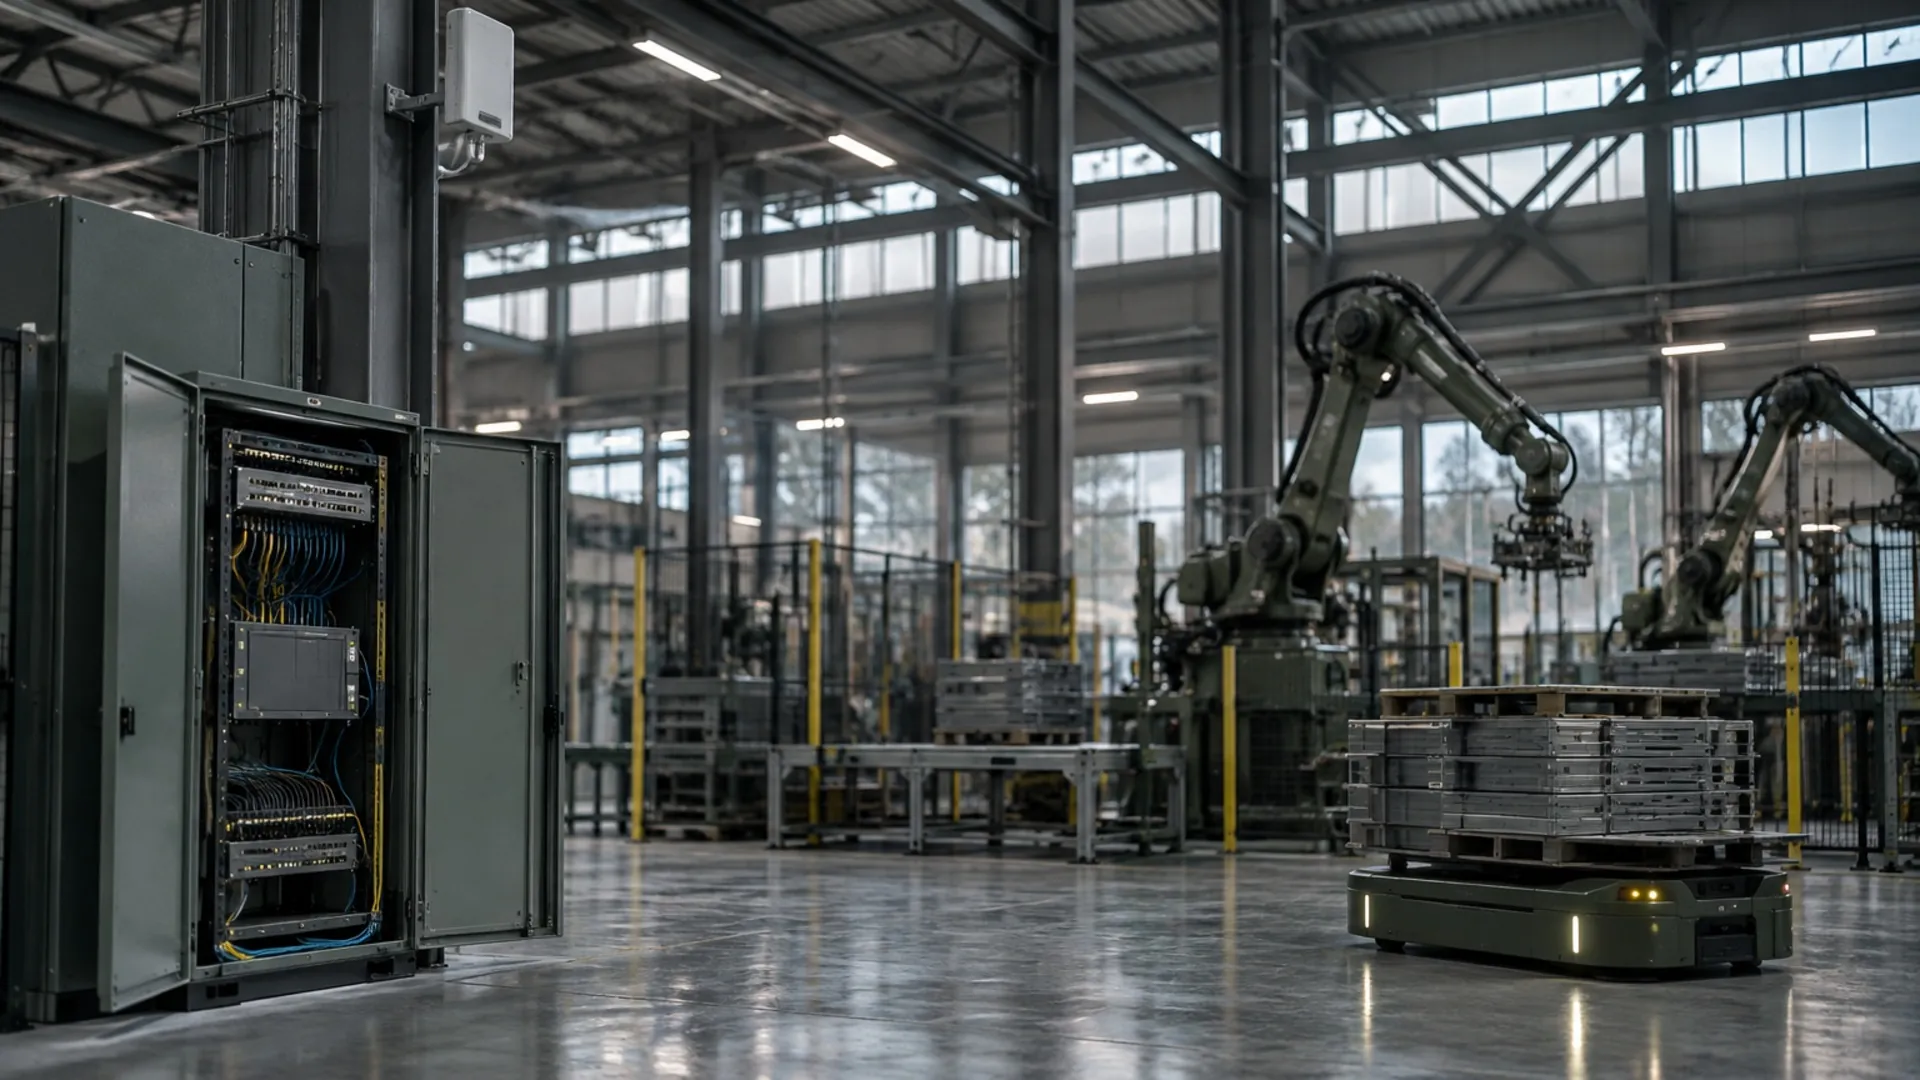
Walk onto a plant floor that switched on private 5G last year and ask who built it. The answer is almost never one company. The radios came from one supplier, the core from another, the SIMs from a third, the routers from a fourth, and a system integrator put the pieces together. Now ask the same team which assets are on that network today, who installed them, and what sits behind each router. That answer does not come from any of the four.
The distance between a network several vendors built and a record of what runs on it became a market story in the second week of October. On October 13, Nokia agreed to sell its Enterprise Campus Edge business. Two days later, Ericsson moved Private 5G into its core networks organization. Neither move is a step back from private cellular. Both say the same thing: the network itself has become infrastructure, and the work has moved to everything that sits on top of it.
Two Moves That End the All-in-One Era
On October 13, Nokia signed a definitive agreement for AURELIUS to acquire its Enterprise Campus Edge business, covering private wireless, industrial devices and on-premises OT edge products. Closing is expected in the first half of 2027. The business serves nearly 900 customers across manufacturing, mining, logistics, airports, ports and power generation.
On October 15, Ericsson announced a simplification of its group structure. Private 5G and Neutral Host move into Business Area Networks, consolidating indoor and enterprise radio work with the core RAN organization. Wireless WAN becomes a standalone business under Market Area Americas. CEO Per Narvinger said the executive team “will be leaner and more balanced in terms of responsibilities.”
For most of the last decade, an enterprise private network arrived as one package. A single vendor supplied the radios, the core, the devices and the integration, and brought partners like us in under the same contract. That model trenched the path for private cellular in industrial environments. It also kept the choices narrow.
From One Vendor to Building Blocks
What replaces it is an integrator’s market. Radios from one supplier, core from another, SIM management from a third, routers and edge compute from a fourth, an automation or AI layer on top, and often a carrier APN running beside the private network. Enterprises are assembling cellular out of building blocks, and the system integrator, rather than the equipment vendor, is increasingly the one deciding how the blocks fit together.
What moved is where the work sits. One analysis of the Nokia deal made the point that private networks were never one market, and that the radio and the core are a thin slice of an industrial project’s budget. Integration, OT connectivity and day-two operations are the thick slice. That slice sits with the plant, the port, the mine and the grid. A network ships. An operational picture does not.
The use cases are live on every front: plants are connecting mobile robots, ports are automating cranes, mines are running autonomous haul fleets, utilities are reaching the grid edge, and carriers are opening their networks to enterprise fleets.
Each signal adds devices someone has to account for.
No Combination Ships a System of Record
Operators chose cellular for control: over coverage, over priority, over who gets on. From what we see with customers, that part is settled. The network is live, built from whichever blocks fit the site, and the question has moved to everything running on it.
They can see SIMs. They cannot always see assets. A SIM tells you something is attached. It does not tell you what it is, who installed it, what firmware it runs, or whether the thing on the pole, the crane or the haul truck today is the thing that was there in March. Teams running SolarWinds, NETSCOUT or ClearPass find the same thing: those tools were built for IP networks, and the cellular layer sits outside their reach.
That is the gap a system of record closes. Not another console for the network, but one authoritative answer to what is on it, that holds whether the pieces came from one vendor or three.
Three Things No Vendor Hands You
Three things stay with you no matter whose radios you buy, and each one is found and fixed differently.
1. Device identity is a different problem from SIM identity. A SIM can move between assets in minutes. Pairing identity to the asset rather than the subscription is what makes an inventory survive a truck roll. On a carrier APN, the SIM is the only identity the carrier gives you, so pairing identity to the asset matters even more.
2. Everything behind the cellular router is invisible by default. One router, one SIM, and anywhere from one to forty assets behind it, none of which appear at the cellular layer. Field teams add and swap them without a change ticket. A router on a plant floor and one on a port crane carry the same blind spot.
3. What one compromised asset can reach is a design decision, not a network feature. Private cellular gives you a flat, reliable path to every site you cover. Segmentation that holds at the cellular layer is what keeps that path from working in both directions. The question is the same on a campus network, a Private FAN or a carrier APN.
Vendors are consolidating the first layer. The second one stays yours.
Where This Goes Next
This matters more every quarter because of what enterprises are putting on these networks. Automation, IoT fleets and AI-driven operations all assume the same thing: that the system knows what is connected, what it is, and what it is allowed to do. Cellular is moving from a connectivity choice to foundational infrastructure for enterprise operations, and infrastructure that operations depend on has to be documented by a system rather than by whoever happened to install it.
An agent that reroutes traffic, a maintenance model that trusts a sensor reading, a production line that adds twenty devices a month: each one is only as good as the inventory underneath it. Give those systems a device list that is three months stale and they will act on it anyway.
The record also has to hold across combinations, because almost nobody runs just one. A private network at the main site, a carrier APN for assets outside the fence, a different vendor at the plant acquired last year. Either there is one record across all of it, or there are three partial ones that disagree.
Questions Worth Asking This Quarter
- How many assets are on the private network right now, and how does that number compare to the asset inventory of record?
- If a SIM moved to a different asset yesterday, who would know, and how?
- What is connected behind each cellular router at the ten largest sites?
- If more than one vendor is on site, which of them owns the list of what is connected?
- If one asset were compromised tonight, what could it reach before anyone noticed?
- Which of the above answers depend on a person remembering, rather than a system recording?
The Part That Stays Yours
The network layer is consolidating, and that is what a growing market does. It specializes. The radios get cheaper, the cores get better, and the suppliers organize around volume. The operational layer moves the other way, toward the operator, because nobody else can own an accurate picture of your assets.
You can buy a network. You cannot buy the picture of what is on it.
Platforms built for this layer establish identity per asset, keep an inventory that updates as the field changes it, and enforce what each asset is allowed to reach, whichever vendors the network is made of. That is the work OneLayer does, as the system of record for enterprise cellular. To see what that looks like on a real network, start with OneLayer Bridge.
It is also the conversation we are having this week at 5G-OT Alliance Connect in Miami, where network owners across manufacturing, ports, mining and utilities are working through the same question. If you are building on private cellular, the 5G-OT Alliance community is where that discussion continues.
OneLayer CEO